Best Credit Cards for Beginners in 2026: Top Picks for First-Time Cardholders
Clarity Flow Core Editorial Note:
We don’t select a “best” beginner card solely by rewards. We consider beginner accessibility, fees, credit-building usefulness, simplicity, and long-term value. Card terms can change, so verify the issuer’s current terms before applying.
Choosing a first credit card is different from choosing a rewards card once you already have established credit. For beginners, approval requirements, annual fees, credit-building potential, and how easily the card fits your spending habits often matter more than a flashy welcome offer.
We compared beginner-friendly cards for several situations, including students, people with no established credit history, applicants with fair credit, people with irregular income, and consumers rebuilding damaged credit.
Quick answer: The best beginner credit card depends on whether you are a student, have no credit history, have fair credit, or are rebuilding damaged credit. There is no single card that is best for every first-time cardholder.
Our top pick depends on your situation. Use the table below to find the category that fits you, then review the card’s current terms before applying.
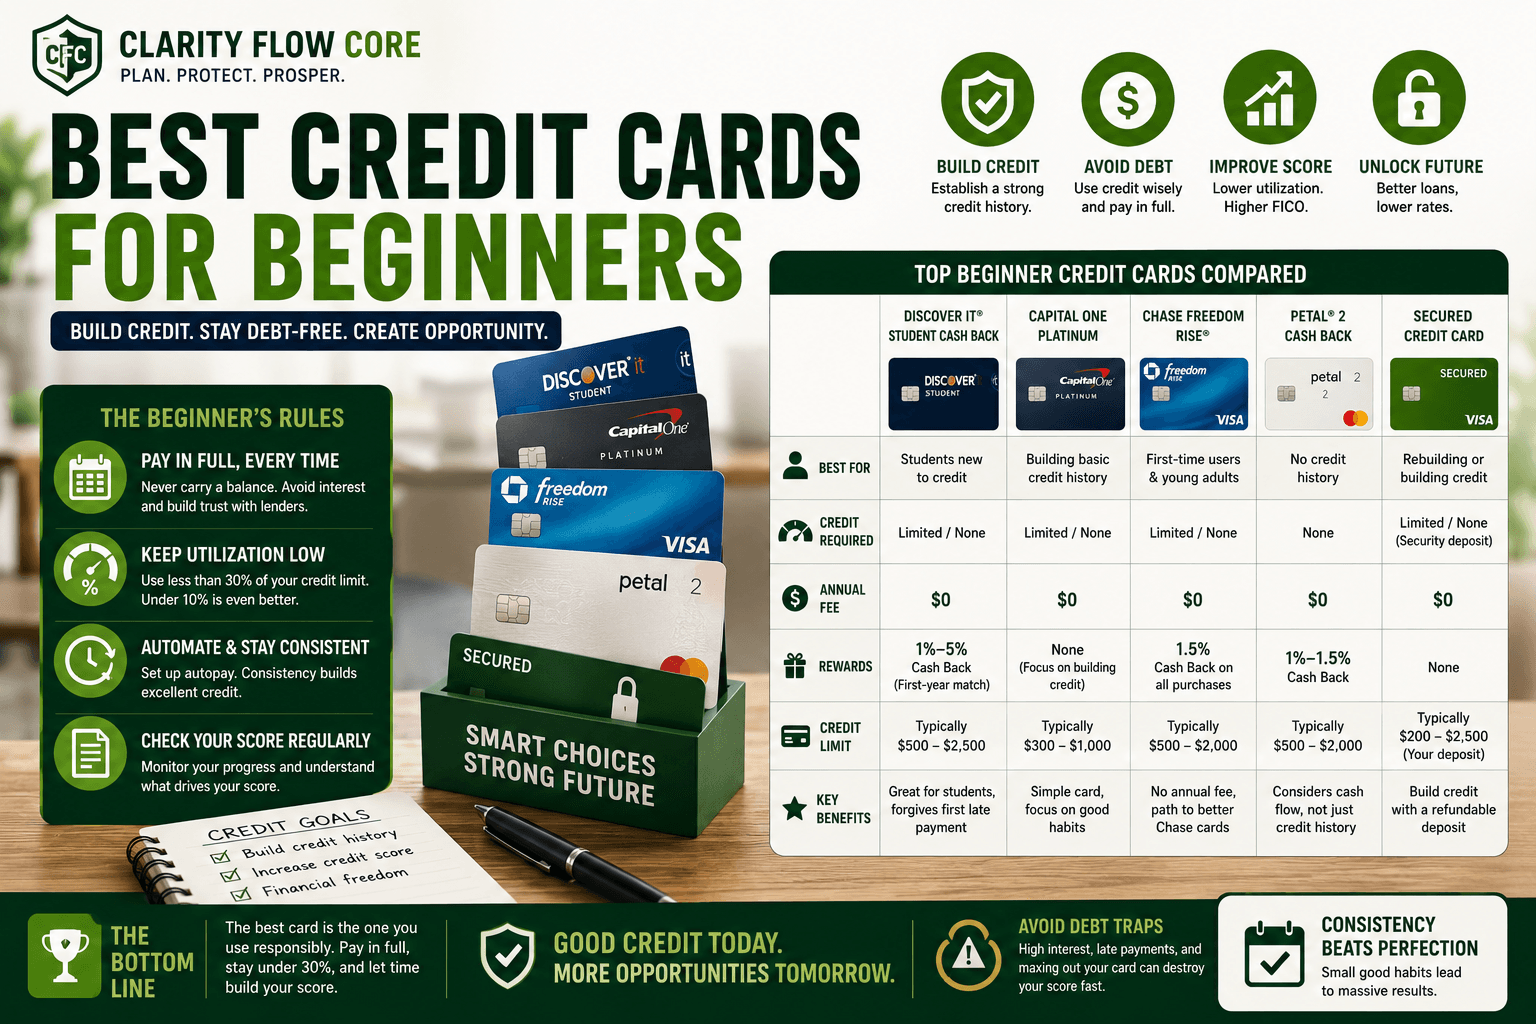
Best Credit Cards for Beginners at a Glance
These are category-based recommendations rather than a universal 1-to-5 ranking, because the best first card depends on your credit profile and situation.
| Card | Best For | Annual Fee | Typical Fit | Rewards | Security Deposit | Key Trade-Off |
|---|---|---|---|---|---|---|
| Discover it® Student Cash Back | College Students | $0 | College students | 5% rotating categories, 1% other | None | Requires active student status |
| Chase Freedom Rise® | New to Credit | $0 | No/limited credit history | 1.5% flat (promotional bonuses vary) | None | $250 in qualifying Chase funds may increase approval odds |
| Capital One Platinum | Building Basic Habits | $0 | Fair credit | None | None | No rewards or cashback program |
| Petal® 2 Visa® | Nontraditional Income | $0 | No/limited credit history | 1% to 1.5% based on on-time payments | None | Cash-flow information may be considered |
| Discover it® Secured Cash Back | Rebuilding Credit | $0 | Poor / Rebuilding | 5% rotating categories, 1% other | Required (as low as $49) | Requires a refundable security deposit |
Important: Card terms, rewards, fees, approval criteria, and promotional offers can change. We verify the information against issuer sources when updating this page.
Which Beginner Credit Card Is Right for You?
Finding the right starting point depends entirely on your current financial profile. Use this decision matrix to narrow down your options:
- I am a college student: Consider student cards. They are tailored to your demographic and often overlook a lack of credit history in favor of your enrollment status.
- I have no credit history: Look for cards explicitly designed for new-to-credit applicants (often labeled as “starter” or “rise” cards).
- I have fair credit: Look for accessible unsecured cards that accept fair histories without requiring premium credit scores.
- I’ve had credit problems in the past: Consider secured cards. Compare their deposit requirements, fees, and graduation policies to find the best path for rebuilding.
- My income is irregular (freelancer/gig worker): Look at cards that accommodate applicants with nontraditional income by analyzing banking history, but don’t assume approval is based solely on cash flow.
How We Chose the Best Beginner Credit Cards
We evaluate starter cards based on the operational realities of a first-time cardholder. Our methodology focuses on:
- Beginner accessibility: Is the card explicitly designed for people with no, limited, or fair credit?
- Total cost: We analyze the annual fee, APR, security deposits where applicable, and other meaningful fees.
- Credit-building usefulness: Does responsible use create a meaningful opportunity to establish or strengthen a credit history through regular credit reporting?
- Rewards relative to complexity: A beginner shouldn’t need a spreadsheet to understand how their rewards work.
- Long-term usefulness: Can the card remain useful after the applicant establishes a strong credit profile?
- Risk of misunderstanding: Are there features, delayed fees, or complex terms that could easily trip up a first-time cardholder?
- Current issuer terms: What does the issuer currently publish regarding their underwriting and fee structures?
Note: We do not treat approval as guaranteed. Issuers use their own underwriting criteria, and approval can vary based on an applicant’s complete financial and credit profile.
Our Editorial Scoring Method
We score beginner cards using the Clarity Flow Core Editorial Score. These scores are our independent editorial assessments, not issuer ratings.
| Category | Weight |
|---|---|
| Beginner accessibility | 30% |
| Annual fees & ongoing costs | 20% |
| Credit-building usefulness | 20% |
| Rewards/value | 15% |
| Features & flexibility | 10% |
| Beginner-friendly simplicity | 5% |
Each card is evaluated against these criteria, and the weighted results inform our category recommendations. Because beginner needs differ, we use the scoring framework to determine which card best fits each situation rather than assigning a universal “best card” title. We reassess the recommendations when material changes to fees, rewards, eligibility criteria, or other important terms occur.
Beginner Credit Card Reviews: Which Card Fits You Best?
Discover it® Student Cash Back — Best for College Students
Why we picked it: Designed specifically for students, with no annual fee and a rewards structure that is relatively straightforward for a first-time cardholder.
What to know before applying:
- Annual fee: $0
- Rewards: 5% cash back on rotating categories (up to quarterly maximums when activated), 1% on all other purchases. Cashback Match for the first year.
- Credit requirement: No credit score is required to apply; Discover may use a credit score if one is available.
- Student requirement: Must be actively enrolled in college.
Pros: Excellent rewards for a starter card; first-year cashback match.
Cons: Rotating categories require manual quarterly activation; limited international acceptance.
Our take: The ideal starting point for enrolled students who want to earn rewards while establishing a positive credit history.
Official issuer information: Discover
Chase Freedom Rise® — Best for New-to-Credit Applicants
Why we picked it: Chase Freedom Rise is designed for people who are new to credit. Its simple cash-back structure makes it relatively easy for a first-time cardholder to understand, while a Chase banking relationship may improve the applicant’s approval chances.
What to know before applying:
- Annual fee: $0
- Rewards: Base 1.5% cash back on all purchases (currently offering a limited-time 3% dining offer for the first 6 months).
- Credit requirement: No/limited credit history.
- Approval note: Chase says applicants who have never had a credit card can increase their likelihood of approval by having at least $250 in qualifying Chase checking or savings funds. The funds are not a requirement or guarantee of approval.
Pros: Simple flat-rate cash back; $0 annual fee; designed for people new to credit.
Cons: The $250 Chase banking provision is not a requirement or guarantee of approval.
Our take: A useful option for applicants who are new to credit and already have, or are willing to establish, a Chase banking relationship.
Official issuer information: Chase
Capital One Platinum — Best for Fair Credit
Why we picked it: Capital One Platinum is a straightforward option for applicants with fair credit who want to focus on managing a credit account responsibly rather than choosing a card primarily for rewards.
What to know before applying:
- Annual fee: $0
- Rewards: None.
- Credit requirement: Fair credit.
- Key features: Automatic consideration for a credit-line increase in as little as six months.
Pros: $0 annual fee; designed for fair-credit applicants; automatic consideration for a credit-line increase in as little as six months.
Cons: Zero rewards or cashback; high ongoing APR.
Our take: A distraction-free credit builder for those who want to establish a solid payment history without the temptation to overspend for points.
Official issuer information: Capital One
Petal® 2 Visa® — Best for Applicants With Limited Traditional Credit History
Why we picked it: Petal 2 can be an alternative for applicants who may not have a traditional credit history. Eligible applicants may have the option to link a bank account so Petal can consider cash-flow information as part of its credit evaluation.
What to know before applying:
- Annual fee: $0
- Rewards: 1%, 1.25%, or 1.5% cash back based on the program’s on-time-payment milestones.
- Credit requirement: Eligibility varies; eligible applicants may be able to link a bank account so Petal can consider cash-flow information as part of its credit evaluation.
Pros: $0 annual fee; cash-flow information may be considered for eligible applicants; rewards can increase with on-time payment history.
Cons: Inconsistent banking cash flow can result in lower limits or denial.
Our take: Worth considering for applicants with limited traditional credit history who may benefit from a cash-flow-based evaluation. Approval and the terms offered still depend on the applicant’s full profile.
Official issuer information: Petal
Discover it® Secured Cash Back — Best for Rebuilding Credit
Why we picked it: This card combines a secured credit structure with a cash-back rewards program and the possibility of transitioning to an unsecured account if the issuer determines that the account qualifies.
What to know before applying:
- Annual fee: $0
- Rewards: 5% cash back on rotating categories (subject to quarterly maximums when activated), 1% on other purchases. First-year Cashback Match.
- Credit requirement: No credit score required to apply; suited for poor or rebuilding credit.
- Security deposit: Refundable security deposit as low as $49.
- Graduation policy: Discover periodically reviews accounts to determine whether a cardholder qualifies to have the security deposit returned and transition to an unsecured account.
Pros: Accessible deposit requirement; reports to all three major bureaus; earns cash back while rebuilding.
Cons: Still requires tying up upfront cash as a deposit.
Our take: It can be a useful tool for establishing or rebuilding a positive payment history when the account is managed responsibly. Compare top offers and deposit requirements in our guide to the Best Secured Credit Cards for Beginners.
Official issuer information: Discover
What to Look for in Your First Credit Card
Before hitting the apply button, ensure you understand exactly what you are signing up for. Evaluate cards based on these core mechanics:
- Annual Fee: A $0 annual-fee card can be attractive for a first account, particularly when you expect to keep the account for several years. Don’t choose a card solely because it has no annual fee; compare the complete fee structure and features.
- APR (Annual Percentage Rate): The purchase APR matters most if you carry a balance. Paying your statement balance in full can help you avoid interest on purchases when the card’s grace-period terms apply.
- Credit Requirements: Ensure the issuer’s required credit profile matches your reality.
- Rewards & fees: Look beyond the advertised rewards rate and check for annual fees, monthly fees, application or processing fees, foreign transaction fees, and other costs that could reduce the card’s value.
- Future flexibility: Consider whether the issuer offers upgrade or product-change options for your account. Availability varies by issuer and card.
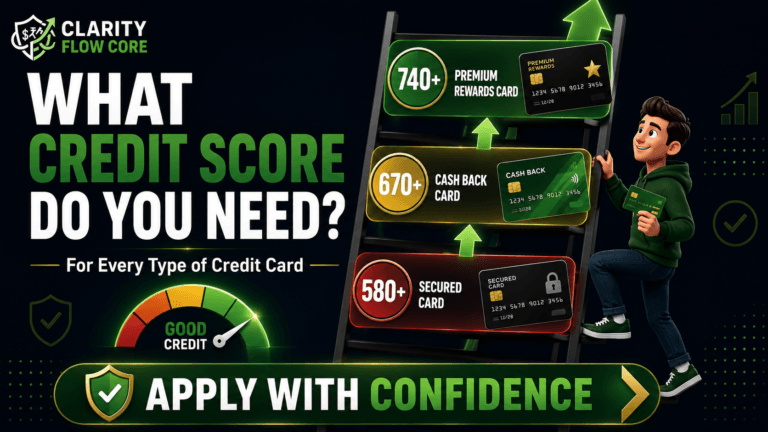
What Credit Score Do You Need for Your First Credit Card?
It depends entirely on the specific card product. Many beginner cards are designed specifically for people with no credit history, meaning you do not need a FICO score to be approved. However, if you are targeting specific tiers or rewards cards, you will need to build your profile first. For a detailed breakdown of what lenders look for, consult What Credit Score is Needed for Each Type of Credit Card.
How to Use Your First Credit Card Responsibly
Getting approved is only the beginning. Consistent, on-time payments and responsible account management are the habits that matter most when you’re building credit.
Your First 30 Days With a New Credit Card
- Day 1: Activate the card and enroll in your issuer’s online banking and mobile app.
- Day 1–3: Set up autopay. Verify whether the payment is set to the statement balance rather than only the minimum payment. If you cannot pay the statement balance in full, make at least the required minimum payment by the due date.
- Week 1: Understand the difference between your Statement Closing Date and your Payment Due Date (explained below).
- Every week: Log in and check your transactions to verify there are no unauthorized charges.
- Every month: Pay the statement balance in full when financially possible.
- Every few months: Review your credit report and account standing.
Statement Date vs. Due Date
- Statement Closing Date: The day the billing cycle ends and the statement is generated.
- Payment Due Date: The date by which the required payment must be received.
Issuers may report account information to credit bureaus on their own schedules, so don’t assume the statement closing date is always the exact reporting date.
How Much Should a Beginner Spend?
There is no required monthly spending amount for building credit. Use the card for purchases you already have room for in your budget. One or two predictable expenses can be enough to keep the account active, but you don’t need to manufacture spending simply to earn rewards.
How Credit Utilization Affects Beginners
Credit utilization is an important part of many credit-scoring models, but there is no universal percentage that guarantees a particular score. A lower utilization ratio is generally better, and keeping reported balances well below your available limit can help.
Many experts recommend keeping revolving utilization below 30%, but this is a guideline—not a scoring cutoff. For a deeper explanation of this metric, read our guide on the 30% Credit Utilization Rule.
Common Beginner Credit Card Mistakes
- Carrying a Balance Does Not Build Your CreditMany beginners mistakenly believe that they must carry a balance and pay the bank interest every month to “prove” they are good borrowers. This is false. The CFPB specifically states that carrying a balance does not build your score, and that paying cards in full each month is preferable to avoid interest.
- The Multiple Application MistakeApplying for several cards in a short period can create multiple hard inquiries on your credit report and may make it harder to manage new accounts. The CFPB advises consumers to apply only for credit they need. Apply only when you have a specific reason to open the account.
- Only Paying the MinimumPaying only the minimum can extend your repayment timeline and significantly increase the interest you pay, especially when the balance carries a high APR. A $3,000 balance at a high APR can take years to repay if you only make minimum payments.
Before You Apply
Before submitting an application, run through this quick checklist:
- [ ] Check your credit report: Ensure there are no errors on your file at AnnualCreditReport.com.
- [ ] Determine need: Verify that you actually need the card and aren’t just applying for a sign-up bonus.
- [ ] Compare costs: Review the annual fees, APR, and any hidden charges.
- [ ] Check eligibility: Ensure your credit profile matches the card’s target demographic.
- [ ] Look for pre-qualification: When an issuer offers pre-qualification, it may use a soft inquiry that does not affect your credit score. An actual application can result in a hard inquiry.
- [ ] Budget check: Make sure your current cash flow allows you to pay the statement balance on time.
Frequently Asked Questions
What is the easiest credit card to get with no credit?
Secured cards can be easier for some applicants to qualify for because the security deposit reduces the issuer’s exposure, but approval is still subject to the issuer’s criteria.
What is the best first credit card for a student?
The Discover it® Student Cash Back is one option worth considering for students who want a $0-annual-fee card with a student-focused application and rewards program.
Should I get a secured credit card if I have no credit?
If you’ve been rejected for unsecured starter cards or are rebuilding damaged credit, a secured card may be worth considering. When the issuer reports the account and you manage it responsibly, it can help establish or rebuild your credit history.
Can I build credit with a secured credit card?
Yes. A secured card is a credit card backed by a refundable security deposit. When the issuer reports the account and you manage it responsibly, it can help establish or rebuild your credit history.
What should I look for in my first credit card?
Focus on the annual fee, credit requirements, APR, rewards structure, security-deposit requirements if applicable, and any fees that could make the card expensive to maintain. The best first card is one you can manage comfortably.
How many credit cards should a beginner have?
One well-managed card can be enough. You can build a credit history with a single, well-managed credit card. You do not need multiple cards simply to build credit. Read more in How Many Credit Cards Should You Have.
Does applying for a credit card hurt your credit?
Checking pre-qualification uses a soft inquiry and does not hurt your score. Submitting an official application triggers a hard inquiry, which can cause a temporary decrease in your credit score.
Should I carry a balance to build credit?
No. Carrying a balance results in interest charges and does not improve your credit score. Aim to pay your statement balance in full every month.
How long does it take to build credit with a credit card?
There isn’t a universal timeline. Someone starting with no credit history generally needs accounts with enough reported history before a scoring model can generate a score, so building credit takes time. The important part is consistently paying on time and keeping balances manageable.
Sources & Verification
Primary Sources
- CFPB — How do I get and keep a good credit score?
- CFPB — Does carrying a balance on my credit card help my credit score?
- CFPB — What is a credit inquiry?
- FTC — Understanding Your Credit
- Federal Reserve — Consumer Guide to Credit Cards
How we update this article
We review card fees, rewards, eligibility language, and other material terms against issuer or regulatory sources when updating this guide. Promotional offers can change between updates, so readers should always review the issuer’s current terms directly before applying.
Disclaimer The information provided in this article is for educational and informational purposes only and should not be construed as professional financial, legal, or tax advice. Every individual’s financial situation is unique. Before making any major financial decisions, consider consulting with a certified financial planner or qualified professional.
About Author

Rishabh Nigam
Rishabh Nigam founded Clarity Flow Core to make personal finance easier to understand for everyday readers. He covers credit scores, debt repayment, credit utilization, loan readiness, taxes, and financial planning through practical guides, calculators, and educational resources. His content focuses on turning complex financial concepts into clear, actionable steps that readers can apply in real life.
3 Comments
Comments are closed.